



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

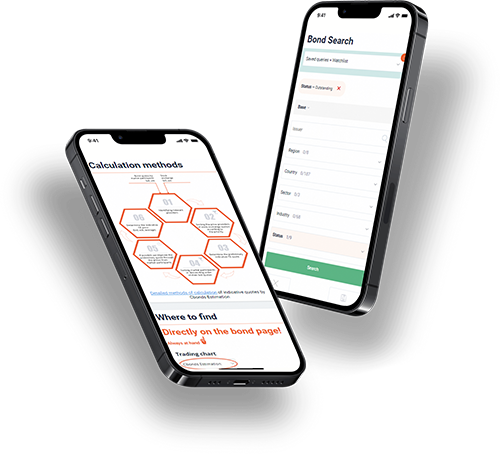
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Mueller Water Products, Q4 2026 Earnings Call Transcript
Mueller Water Products delivered record fiscal 2026 results, with sales up 3.2% to about $1.5 billion, adjusted EBITDA up 14.1% to $372 million and margin reaching 25.2%. Management attributed gains to pricing, productivity, manufacturing performance and specialty-valve growth, while lower volumes, inflation and tariffs remained pressures. The company plans to transition its metering business to Zenner, expecting about $26 million in one-time fiscal 2027 costs and an annualized EBITDA benefit of $8 million, or 100–140 basis points of margin expansion, mainly from the second quarter.
For fiscal 2027, Mueller forecasts sales of $1.44–$1.47 billion and adjusted EBITDA of $378–$388 million, implying a 26.3% margin at the midpoint. Guidance assumes low- to mid-single-digit pricing gains, double-digit specialty-valve growth and flat consolidated volumes excluding the prior-year hydro backlog benefit. Growth is expected to be constrained by weaker residential construction, cautious municipal spending, lower hydrant volumes, inflation and tariffs; management expects stronger sales and margins in the second half.