



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

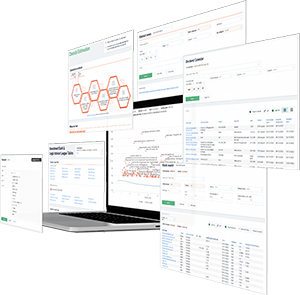
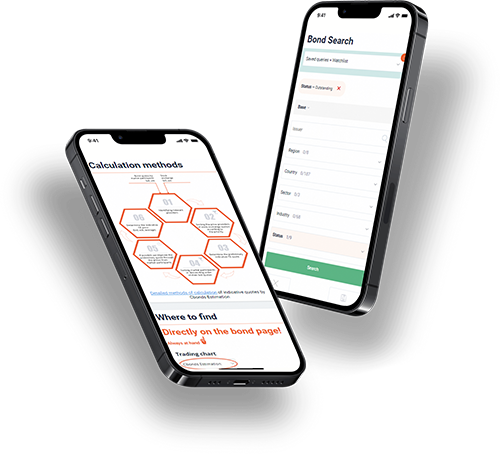
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
MP Materials, Q3 2026 Earnings Call Transcript
MP Materials reported higher NdPr output and sales in Q3, while commissioning heavy rare-earth separation and qualifying magnets for GM shipments beginning in Q4. The company expects Q4 NdPr volumes near 1,000 metric tons and realized prices around $100/kg. Commercial dysprosium and terbium production is starting, primarily to supply its magnet business; management says current prices for some medium and heavy rare earths are unusually high and may not persist. NdPr production is expected to exceed a 5,000-ton annual rate in 2027, with cost improvements more visible in the second half as new facilities stabilize.
Magnet sales are expected to build gradually, starting modestly before increasing in late 2027; the segment’s adjusted EBITDA contribution should remain modest that year, with its full earnings potential clearer in 2028. Management sees growing customer interest in robotics and other magnet markets, but cautions that timing and winners are uncertain and expects a difficult year for parts of the industry. It plans to preserve financial flexibility and remain disciplined with capital as it executes contracted customer commitments.