



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

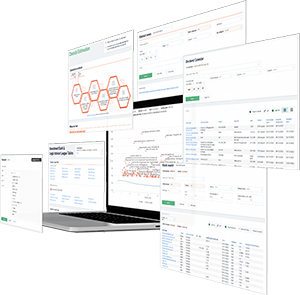
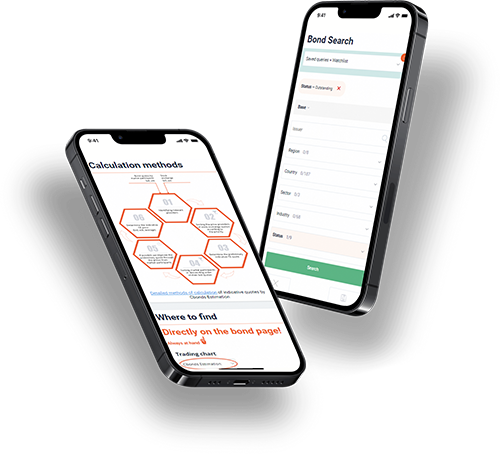
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
The Joint Corp, Q3 2026 Earnings Call Transcript
The Joint’s third-quarter comparable sales improved sequentially to -1.9%, but consumer spending pressure continued to weigh on new patient visits and monthly spending. Active membership, conversion, retention and patient lifetime value improved, supported by flexible plans and lapsed-patient outreach, though lower near-term spend per patient has so far offset those gains. Revenue rose 1% year over year, while adjusted EBITDA from continuing operations increased to $2.3 million as the capital-light franchisor model strengthened profitability.
Management expects 2026 system-wide sales of $508–512 million and comparable sales of -3.5% to -2.5%, while maintaining adjusted EBITDA guidance of $12.5–13.5 million. The clinic base is expected to end the year about 50 locations below 2025 levels, with growth resuming next year. New clinics are reaching breakeven faster, and a planned AI-powered lead platform could begin contributing to comparable-sales growth in 2027; the priority remains restoring positive comps amid continued consumer pressure.