



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

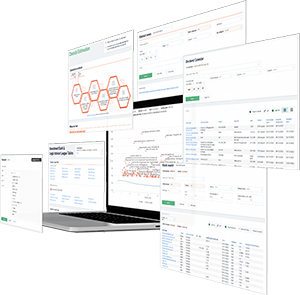
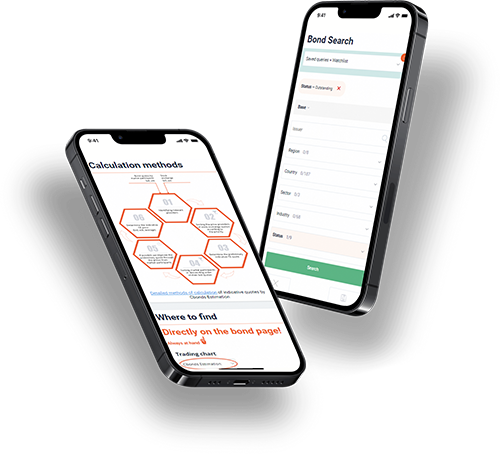
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Huntsman Corporation, Q3 2026 Earnings Call Transcript
Huntsman expects another year of challenging conditions, with weak housing, high energy and mortgage costs, subdued consumer confidence and China’s export-led growth weighing on chemicals. Even so, cost, pricing and operating discipline are expected to lift 2026 EBITDA by more than $100 million versus 2025. Management sees MDI industry growth in 2027 at around 2%, similar to 2026, while new North American supply may make the market bumpy as it replaces imports. Higher European energy costs make price increases and supplier management a priority.
The Olin merger, expected to close early next year, is intended to deliver $300 million in synergies, plus another $100 million as chlorine contracts expire, and broaden supply-chain integration and portfolio flexibility. Huntsman expects 2027 to be materially better than 2026, citing further cost opportunities and growth in aerospace, power infrastructure and other Advanced Materials applications; this business is forecast to maintain GDP-plus growth. Housing and construction remain soft, while European operations will focus on attractive growth markets and reducing exposure to energy-intensive areas.