



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

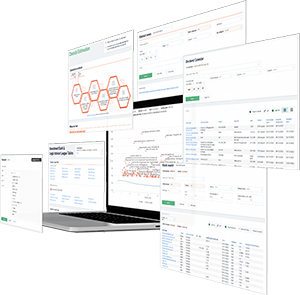
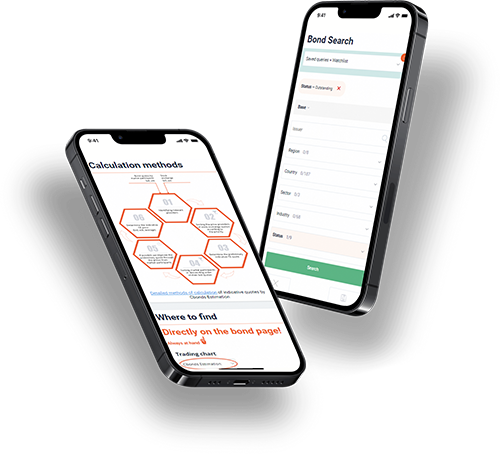
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Gibraltar Industries, Q3 2026 Earnings Call Transcript
Gibraltar Industries lowered its 2026 outlook after a sharper-than-expected slowdown in residential demand, with U.S. shingle shipments down 13% year over year in Q3 and weakness concentrated in the Southeast and Southwest. Management cited both softer end demand and customer destocking, alongside higher steel, fuel and logistics costs. Agtech revenue was also pushed into 2027 by permitting delays and customers rescheduling projects, while Infrastructure sales fell amid delayed municipal pilots; the company expects to sell the Infrastructure business and use proceeds to reduce debt.
Despite the headwinds, residential sales grew organically and the business outperformed market growth in four of five regions. OmniMax integration synergies have exceeded the original three-year target within eight months, and management expects further savings. Revised continuing-operations guidance implies lower sales, margins, earnings and free cash flow; Gibraltar expects debt reduction to remain the priority, with net debt targeted below $800 million by early 2028. Management sees Agtech project demand building and plans to share its 2027 outlook early next year.