



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

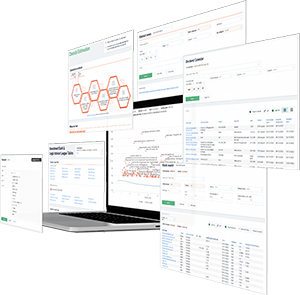
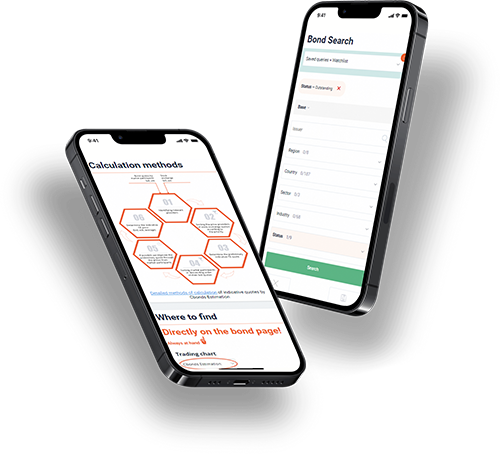
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Natural Resource Partners, Q3 2026 Earnings Call Transcript
Natural Resource Partners generated $45 million in free cash flow in Q3 2026 and, after repaying $13 million of debt, raised its distribution to $2.34 per unit. Management says quarterly payouts will remain subject to the board’s assessment of results, liquidity needs and alternative uses of cash. Mineral Rights continued to provide dependable cash flow, but weak global steel demand is limiting metallurgical coal prices, while cheap natural gas and ample utility coal weigh on thermal coal. NRP sees no clear sign of a material change in coal pricing in 2027.
Soda ash remains oversupplied, with weak demand and international prices below most producers’ costs; domestic prices are expected to decline as contracts reset, making 2027 more difficult than 2026. Capacity closures are starting, but management expects market rebalancing to take years. Sisecam Wyoming’s low-cost operations and ongoing cost reductions are intended to support competitiveness through the downturn; distributions from the business are not expected to resume until demand rebounds or supply responds significantly.