



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

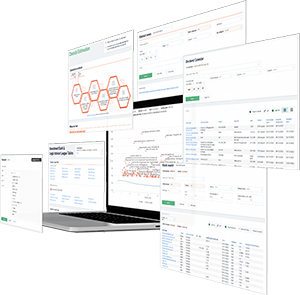
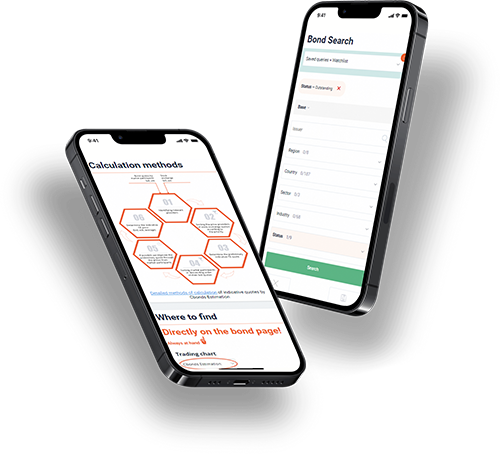
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Fortune Brands Home & Security, Q3 2026 Earnings Call Transcript
Fortune Brands lowered its 2026 outlook as single-family new construction weakened, customers turned more cautious and the company plans to reduce channel inventories. Fourth-quarter sales are now forecast at $925 million–$995 million and EPS at $0.19–$0.29; full-year sales are expected at $4.205 billion–$4.275 billion, with EPS of $3.20–$3.30. Water remains under pressure from softer demand, service costs and missed price realization, while aluminum and freight costs have compressed Larson’s margins. Management expects Water’s recovery to take longer than improvements in Doors and Security.
The company is realigning teams around business units, selling Fiberon, exiting China’s domestic commercial operations and rationalizing Water’s EMEA footprint. These moves and other initiatives are expected to deliver more than $120 million in annual benefits as the company exits 2027; the full improvement is expected to become visible in Q4 2027, after near-term headwinds. Management targets EBITDA margins above 20% and above-market growth, while emphasizing that the turnaround will take time.