



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

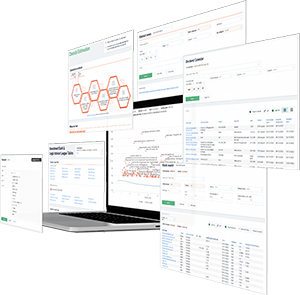
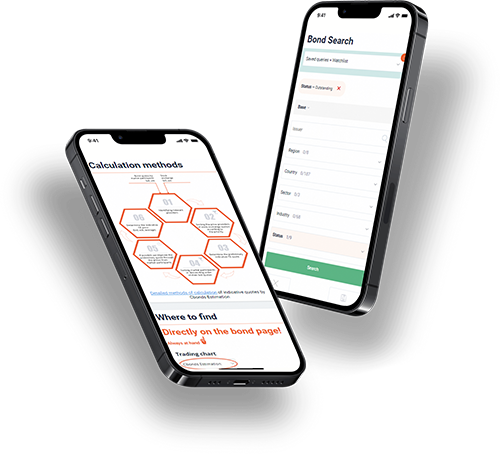
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Advantage Solutions, Q3 2026 Earnings Call Transcript
Advantage Solutions posted 1% third-quarter revenue growth, its fourth consecutive quarter of growth, while adjusted EBITDA fell 12% amid planned investment and weakness in Branded Services. Experiential Services revenue rose 12% on strong demand, and Retailer Services returned to growth; Branded Services remained pressured by client losses and unfavorable mix. Management expects double-digit revenue and adjusted EBITDA growth with margin expansion in Experiential Services in Q4 and for the full year, while Branded Services is expected to improve sequentially and move toward stabilization in 2027.
The company reiterated full-year guidance for flat to low-single-digit revenue growth and adjusted EBITDA flat to down mid-single digits, alongside $250 million–$275 million in adjusted unlevered free cash flow. A restructuring underway into 2027 is expected to deliver about $25 million in annualized net savings, with more savings planned over time. Management cited rising energy prices and interest rates as sources of greater uncertainty, and noted that project timing and the pace of Branded Services restructuring could affect Q4 results.