



Explore the most comprehensive database
1 000 000
bonds
100 000
stocks
175 910
ETF & Funds
100 000
indices
Track your portfolio in the most efficient way

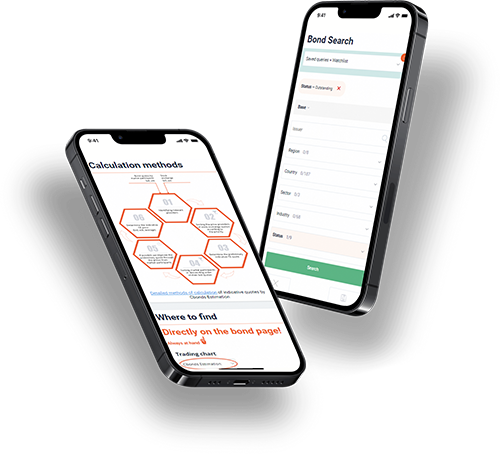
full data on over 1 000 000 bonds, 100 000 stocks, 100 000 indices, 17 000 ETF and 150 000 Mutual Funds; powerful bond screener; over 350 pricing sources among stock exchanges & OTC market; ratings & financial reports; user-friendly interface; available anywhere via Website, Excel Add-in and Mobile app.
Register


 Bond Screener
Kontoor Brands, Q3 2026 Earnings Call Transcript
Kontoor is shifting its focus to Wrangler and Helly Hansen after completing the sale of Lee, with $450 million in planned share repurchases and $280 million in voluntary debt payments. Third-quarter revenue from continuing operations rose 3% to $685 million, while adjusted gross margin expanded 32 basis points and adjusted EPS increased 40%. Wrangler growth was supported by direct sales, women’s products and international markets, but softer point-of-sale trends and cautious retailer inventories have tempered its near-term outlook. Helly Hansen performed in line with expectations, with management targeting faster growth in the U.S., premium outdoor and workwear.
For 2026, Kontoor expects revenue of about $2.68 billion and adjusted EPS of $5.40, up 31%; adjusted gross margin is forecast at 50.0%–50.2%. Management expects at least $6.60 in adjusted EPS in 2027 and sees earnings power above $7 over the next 12–18 months. Risks include subdued consumer demand, conservative retail inventories, supply-chain volatility, higher freight costs and tariffs; the company anticipates roughly $30 million of incremental tariff expense in 2027 if current rates persist. Cash flow is expected to exceed $400 million beyond 2027.